
Financials · Notes
Did my insurance agency acquisition pay for itself?
Short answerAsk whether the purchased clients are still with the agency, then ask what the deal has earned back. The first answer comes from dated snapshots of the AMS's book of business report. The second compares the price with acquired-book commission after payouts and financing costs. A single premium total cannot answer both.
John RanieriFounder & Product Lead, Keelridge SoftwareSeptember 12, 2026 · 7 min read
Why doesn't the purchase price answer whether the deal worked?
A purchase price records what the buyer agreed to pay. It does not show how much of the purchased client base remained, what that book produces now, or how financing and accounting charges affect the agency after closing.
That is why post-close review matters. Insurance Journal's 2026 discussion of agency acquisition economics argues that amortization, interest, tax allocation, and owner distributions can make actual results diverge from the original projection. Keelridge does not replace a full deal model, tax analysis, or valuation. It gives the owner a recurring operating view of the parts supported by the agency's book, deal facts, and mapped ledger accounts.
How can an owner tell whether the acquired book is still here?
Give each acquired book a stable identity, record when it became the agency's responsibility, and follow its client and premium history across dated AMS snapshots. Client count is the clearest survival signal because premium can rise with rate, exposure, or coverage even while relationships leave.
The first months need special care. A purchased book may appear gradually as policies renew and are rebooked onto the buyer's AMS. Those accounts are the purchased book moving onto the system, not organic new business. Clients who leave count as lost from day one, while new clients sold under the acquired book's codes show as new clients. A client whose same policy comes back within 14 months, after a gap in the records, is treated as retained, not lost. In Keelridge this is Acquired books, under Planning; the table below uses its words.
| Movement | Classification | Why it matters |
|---|---|---|
| Start | Clients on the book's codes when tracking begins | The first supported view of the purchased asset |
| Moved over | Purchased clients rebooked onto the agency's system after the start | Part of the acquisition arriving, not organic growth |
| New clients | New clients written under the book's codes after it became yours | Growth created after closing |
| Lost | Clients from the acquired book who left the agency | Attrition against what the agency purchased |
| Lines dropped, rate and exposure, new lines | The premium change on clients held at both dates | What the clients who stayed dropped, what their policies renewed at, and what they added |
| Now | Clients on the book's codes at the latest snapshot | The current client base on the acquired book's codes; the steps above should reach it. A line back after a gap in the records shows on its own row as Returning, counted as retained |
What does 'paid for itself' mean?
It needs an explicit definition. Keelridge's deal-payback estimate credits the commission on every policy term under the acquired book's codes that started after the book became the agency's. Each term counts once, in the month it starts, which is when the ledger books it. It also credits what the book paid after closing on policies written before it (a policy still in force at closing, or a premium audit), in the month the book became the agency's. It subtracts the 1099 producer payouts on those terms and each month's note interest, then compares the running total with the purchase price. The purchase price includes the down payment plus note principal; principal payments are not subtracted again because they repay that same price.
This is an estimate of operating results, not cash-basis accounting. Where the agency's AMS records less commission than its ledger, the estimate is conservative; that assumption is stated beside the figure. A book bought before the agency's first snapshot on file shows a floor, not a full history. The estimate does not invent overhead, tax, or integration costs that the available records cannot attribute to one book.
The result should therefore be read as estimated purchase-price recovery from attributable book earnings. It is useful for comparing the deal with its own history and assumptions. It is not a certified investment return or a replacement for the agency's accountant, lender, or transaction adviser.
Why should accounting net and cash net stay separate?
Amortization is an accounting charge; principal repayment is a cash outflow. Combining them into one unlabeled net number makes the deal look more or less burdensome depending on which basis happened to be used.
| View | A useful calculation | What it answers |
|---|---|---|
| Bought clients kept | Clients, premium and commission from the purchase still with the agency, wherever they are coded now | What is left of what you bought. A bought client moved to another producer code still counts; a new client written under the book's codes does not |
| Last 12 months, after charges | Commission booked over the last 12 ledger months − 1099 payouts on those terms − amortization − interest, all over the same 12 months | What the book leaves after mapped income-statement charges; amortization is non-cash |
| Next 12 months, after note payments | Commission booked over the last 12 months − payouts − note payments (principal and interest) due in the next 12 months; assumes the next 12 months book what the last 12 did | Whether current attributable annual commission covers annual debt service |
| Deal payback | Cumulative booked commission − payouts − interest, compared with purchase price | How much of the agreed price the book has approximately earned back |
Which records are needed for a defensible monthly review?
The minimum useful package is a sequence of dated snapshots of the AMS's book of business report, a confirmed acquisition identity or producer-code map, the date the book became the agency's responsibility, and the agreed purchase price. Commission, seller or producer payouts, note terms, and the mapped amortization and interest accounts make the economics more complete.
Missing records should remain visible. If the acquisition date is unknown, the observed trend is only the history on file. If an accounting account or statement period is missing, the related charge is unknown, not zero. If an executive code might represent both acquired business and an active producer payout, the owner needs to confirm the treatment before relying on the result.
- snapshots of the AMS's book of business report. Client, policy, premium, commission, and the stable codes that identify each acquired book.
- Acquisition facts. Close or service date, purchase price, down payment, note principal, rate, and term.
- Accounting mappings. The GL accounts that contain amortization and note interest for each deal.
- Payout treatment. Any seller, producer, or 1099 share that remains attached to the acquired policies.
- Human confirmation. Owner approval of the codes, dates, terms, and exceptions that source reports cannot infer safely.
What does Keelridge automate after setup?
A one-time acquisition model becomes stale unless someone updates the book, refreshes the ledger period, maintains the code map, and rebuilds the same comparisons. Keelridge carries those confirmed rules into the recurring agency review.
When the agency supplies its regular AMS book and income-statement files, Keelridge stages and validates the new period, refreshes the annual commission of current acquired books and mapped charges, extends the per-book retention history, and updates the payback estimate. The owner can see the agency-wide roll-up, open one acquisition, and trace the figure back to its source and definition without rebuilding a separate workbook each month.
For each book with a recorded price and date, Acquired books shows the price paid, the dollars and share of it earned back so far, and the month it should break even at its recent pace. It charts each book's 12-month retention beside the agency's own, shows what the book added since the purchase (clients moved over, new clients, clients lost and how the retained clients' premium changed), and gives the multiple paid at closing, the effective multiple, the next 12 months of debt service and the note schedule. A change of ownership is shown apart, with no payback and outside the totals. A book with no price or date shows no payback, and a book bought before the earliest book file on record shows its amount earned back as 'at least'.
The product does not decide whether to buy an agency, declare that a transaction was good, or replace legal, tax, accounting, or valuation advice. It keeps the post-close operating figures current enough for the owner and advisers to ask better questions.
What this looks like in the owner demo
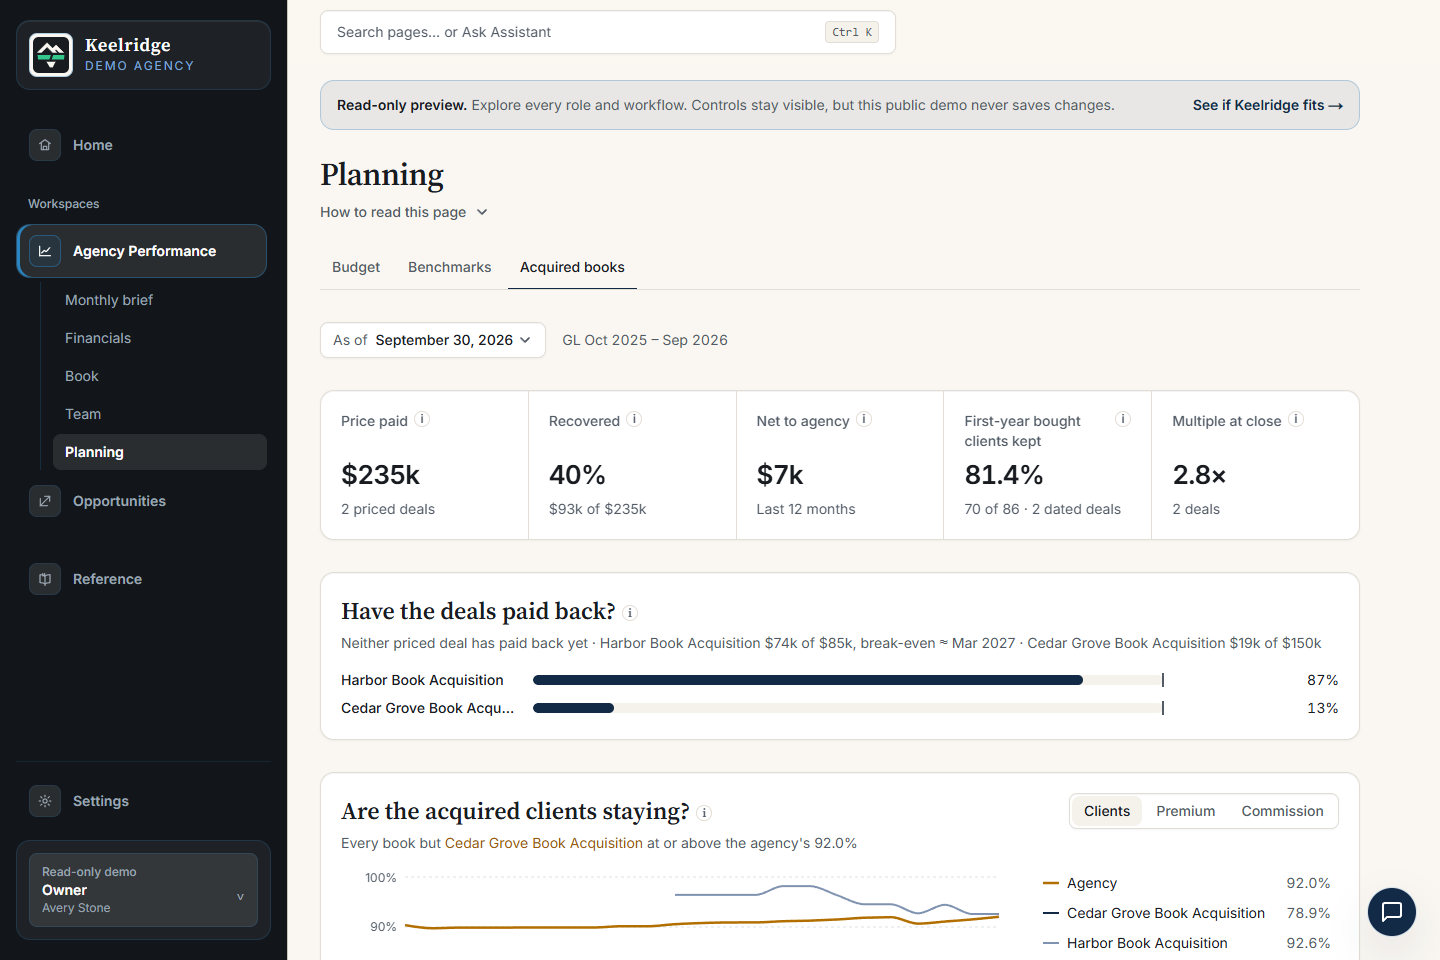
Have the deals paid back, and are the bought clients staying?
 Owner viewOpen this page in the live demo →
Fictional Keelridge Demo Agency, as of September 30, 2026. Acquired books opens with the price paid, how much has been recovered, what the books left the agency over the last 12 months and how many bought clients were kept in their first year. Below sit a bar per deal for payback and each book's client retention against the agency's. In the demo, two deals cost $235k and have recovered 40%; neither has paid back yet, and one is expected to break even around March 2027.
Review the asset and the financing as two connected stories
First ask whether the purchased client relationships remain, using client movement across dated book snapshots. Then ask what the deal has earned back, with the purchase price, attributable commission, payouts, interest, accounting charges, and cash debt service kept on clearly labeled bases. That is more useful than one acquisition ROI percentage whose inputs and period cannot be reconstructed.
Sources used for the industry context
- Insurance Journal: Why Post-Close Economics Determine Acquisition SuccessIndustry discussion of why amortization, interest, tax allocation, and owner distributions can cause post-close results to diverge from an acquisition projection.
- Insurance Journal: 8 Things to Consider When Buying or Selling an Insurance AgencyLegal and transaction context on client attrition, renewal-contingent purchase terms, earn-outs, and post-close risk in agency transactions.
- Big ‘I’ and Reagan Consulting: Best Practices Foundations: GrowthIndustry methodology distinguishing acquisition and divestiture activity from conventional organic growth while preserving retention and new business as separate drivers.