
Guided owner tour · 5 steps
What is turning into new business?
Review open opportunities, what the team has won or lost, and what later arrived in the book. Use the figures to decide where work needs attention and how sales activity is contributing to agency growth.
KEELRIDGE SOFTWARE · REVIEWED · Screens come from a fictional, read-only agency.
 Owner viewOpen this page in the live demo →
The short answer
Review the pipeline and the book together.
Where does open work need attention?
See what is in progress, which quote dates have passed and who is responsible. Give the team a starting point for the next review.
What are we winning and losing?
Read wins and losses, annual bound premium and recorded loss reasons together. Open the opportunity behind a result.
What is contributing to growth?
Review later Book arrivals and their classification, then decide what to investigate or support next. People connect the sales and book figures.
Where does the open work need attention?
Where: Opportunities, Overview.
Start with what is open today and which quotes are overdue. The Overview shows Bound premium, Close rate, Came in and Open. In the demo, over all time: $1.39M bound premium, a 72% close rate, 364 requests came in, and 24 are open today with 10 quotes overdue. Intake staff and department managers keep each opportunity up to date as work happens.
Keep one opportunity per insurable account, with its dates, department, an estimated premium on each quoted line and assignment. The Overview separates activity in the selected period from the queue open now: came in, bound and lost use their own dates.
Explore the all-time Opportunities view as owner →
Owner viewOpen this page in the live demo →
Are opportunities turning into wins?
Read the number of wins and losses beside close rate and annual bound premium. A high percentage on a small number of decisions tells a different story from a busy period with the same rate. Inspect recorded loss reasons when deciding where to investigate.
Close rate is bound divided by bound plus lost among opportunities resolved in the selected period. Open work stays outside the denominator. Bound premium sums annual premium on policy lines bound in that period; open estimated premium describes the current pipeline, not a revenue prediction.
Owner viewOpen this page in the live demo →
Who owns the work, and what context do they need?
Review what came in, was bound or was lost, and annual bound premium, by the account manager or producer currently assigned. Use Group by to switch between the two. Open the opportunity behind a result to understand a handoff, clarify who is responsible or agree the next action.
Owners and executives can review both departments. Department managers and authorized intake staff work within their permitted department scope. An account manager sees opportunities only when given access by name, and only people with full control can export the list to Excel.
See new business by account manager or producer in the fictional owner demo → Owner viewOpen this page in the live demo →
What actually showed up in the book?
Read the opportunity result alongside later book movement from the AMS. A bound line may appear only after its effective date and a later export. On the book, arrivals split into new clients, new lines and acquired books. A policy moved to another carrier is a rewrite and stays in the retained book.
Where: Agency Performance, Book, Growth.
The two views answer different questions. Keelridge does not automatically match a bound opportunity to an AMS arrival. People check timing and classification before treating pipeline results as growth.
Why policy-level reporting inflates new business →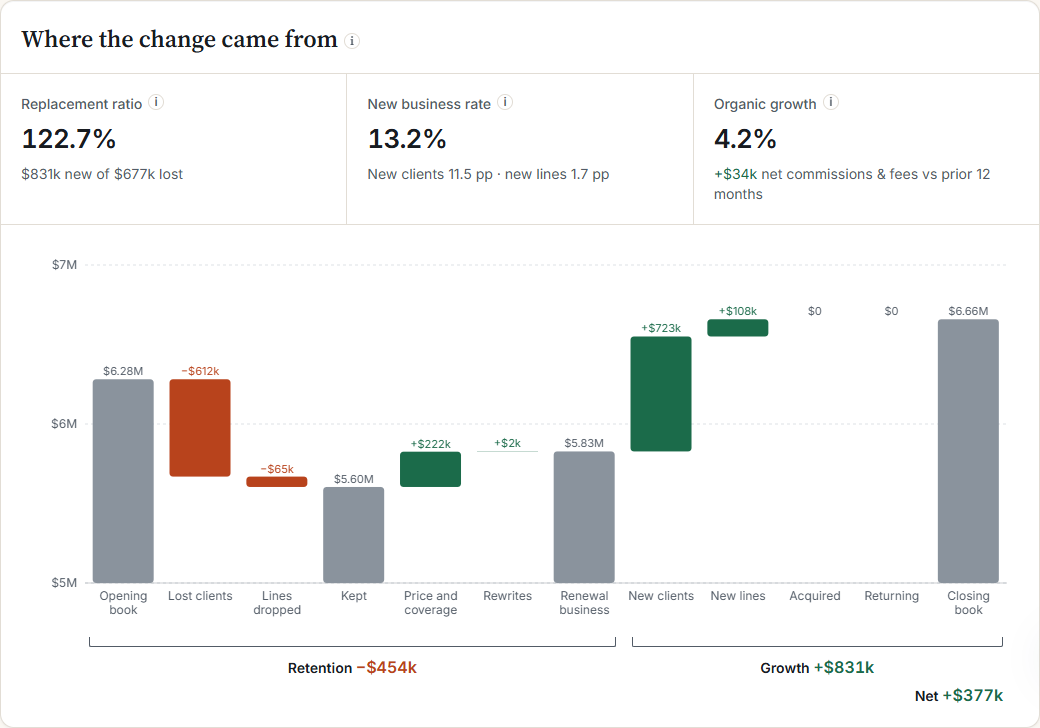 Owner viewOpen this page in the live demo →
Keep the figures current. Agree what happens next.
Answering what is open and what the agency is winning should not require asking each person to rebuild a report. People keep opportunities up to date as work happens. The owner, or someone the owner authorizes, uploads supported AMS book reports, reviews the checks and confirms the update, keeping the book's movement current.
Use the recurring management review to decide where the team needs help, which losses deserve investigation and what later Book growth needs explaining. One agency context supports financial, book and team review, with the views and context each role needs. People own status changes and follow-through; authoritative policy and service work stays in the AMS.
See the point-to-point book premium bridge →Before drawing a conclusion
Keep sales activity and book growth clear.
- Compare the right dates and basis.Came in, bound and lost use their own dates. Open work is a current queue; reported bound premium is annual.
- Classify what entered the book.A policy number alone cannot establish a new client relationship. Keep rewrites and bought books apart from new clients and new lines.
- Bring human context to responsibility.Assignment shows responsibility for the record; it does not establish who caused a win or loss. Handoffs, role, tenure and opportunity mix matter before judging a person.
- Keep decisions with the agency.People record outcomes and own follow-through. The tracker does not quote, send reminders, change status automatically or write to the AMS.
Questions from agency owners
Before using pipeline activity as a growth measure.
How should an insurance agency track new business?
Keep one opportunity per insurable account, with its dates, who is responsible and an outcome a person records. Review open work beside what came in, was bound or was lost in a set period. Then check later AMS book movement to tell new clients and new lines apart from rewrites and bought books. Keelridge does not automatically match a bound opportunity to an AMS arrival.
Read the note →What is an insurance agency close rate?
Close rate is bound divided by bound plus lost among opportunities resolved in the selected period. Bound uses the date marked bound; lost uses the date marked lost. Open opportunities stay outside the denominator. If nothing was resolved, the rate is unavailable rather than zero. Read volume and annual bound premium beside the percentage. In the demo: 72%, 245 bound of 340 closed.
Why can bound premium differ from new premium in the AMS book?
Opportunities reports annual premium from the bound policy lines people record. For a six-month line, that annual amount is twice the entered term premium. Older lines without a recorded term retain their annual basis. The AMS book shows policies present in a later snapshot. Effective dates, entry timing, cancellations and policy changes can create differences; the agency investigates them without an automatic record match.
Does a new policy number prove new business?
No. A rewrite or carrier move for a client already on the book can create a new policy number without creating a new client relationship. Keelridge keeps a rewrite in the retained book and counts only its price change; new business is new clients and new lines.
Read the note →Your agency’s growth questions
Start with the new-business review you want to improve.
Keelridge is free for five design partners until February 15, 2027. It starts with a 20-minute fit call, where we walk through Keelridge using fictional agency data. Discuss how you review open work, wins and losses today, where the management picture gets rebuilt by hand and who needs the resulting context. No agency files are needed for the conversation.