
Operations · Notes
How should an insurance agency measure account manager performance?
Short answerStart with the book the account manager was responsible for. Read client retention, premium renewed, new business, lost business and rounding over the same period, then account for assignment history, hand-overs, workload and service context. The figures support coaching; they do not produce an employee score.
John RanieriFounder & Product Lead, Keelridge SoftwareAugust 30, 2026 · 7 min read
What are you actually trying to measure?
An account manager's job is not simply to hold the largest book or produce the largest dollar total. It is to help the agency retain relationships, navigate renewals, develop existing accounts, and keep a changing book under control.
That means the first step is defining the role. If one account manager is expected to source new clients while another primarily services a producer's book, the same new-business target cannot describe success for both. If the agency has never agreed on what the role owns, a dashboard will only make the disagreement more precise.
The useful question is narrower: given the book this person was responsible for, what happened to it during the period, and which parts could the person reasonably influence?
Why is current book size a poor performance measure?
Book size is a stock. It describes what is assigned to someone today, not what they did to create, retain, or develop it.
A large book may have been inherited from a retiring producer, transferred from a colleague, or added through an acquisition. A smaller book may belong to a newer account manager, contain more complex commercial accounts, or have started the year much smaller. Ranking those two people by current premium or client count confuses assignment with performance. The same applies to commission in an owner/executive economic review.
Book size still matters because it describes responsibility and workload. It belongs beside performance measures as context, not above them as the verdict.
Which numbers should an owner read together?
No single number can describe an account manager's contribution. A useful monthly review keeps several readings beside one another so that each can challenge the others.
In Keelridge, department managers and account managers see premium within their scope, not commission or payout figures. Department managers review their team’s retention, growth, rounding and assigned-book premium; account managers review their own book. The owner-facing economic analysis below does not imply commission access in those workspaces.
- Client retention. Of the clients assigned at the start of the period, how many are still with the agency? This is the cleanest relationship measure because every client counts once.
- Premium renewed. How much of the book this person serviced renewed, at this year's price. The book serviced is what they held a year ago, plus clients handed to them and less clients handed away, each at last year's value. From it, take away lost clients and dropped lines, then add rate and exposure changes and rewrites. A client lost after a hand-over counts for the person who received it; one lost before it counts for the person who handed it over. Read it beside client retention: account size and price changes can make it stronger or weaker than the client count.
- New and lost business. Which clients arrived or left, which arrivals came with a purchased book, and which clients already on the book added a line? New business is new clients plus new lines. A policy rewritten to the same coverage, or moved to another carrier, is retained business, not one win and one loss; only its price change counts.
- Rate and exposure. Did premium on the policies that renewed rise or fall? This captures rate, exposure, coverage, and mix together, and it is inside premium renewed. It is important, but it should not be presented as if the account manager caused every change.
- Rounding. How many clients added a policy this year, and how many policies does each client hold on average? Keelridge shows both: Accounts rounded and Policies per client. A client who dropped a line is a retention matter and is not netted off. Net cross-sell, new lines less lines dropped, puts the two sides together.
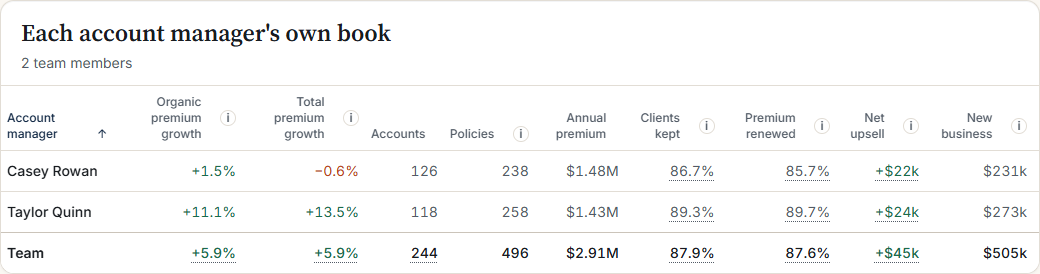
- In Keelridge. The team view reads client retention, premium renewed, new business and net cross-sell, beside organic and total premium growth. Organic premium growth leaves out clients handed over and purchased policies in their first 12 months; total premium growth leaves them in, so the gap between the two is what was moved or bought, not sold.
- Owner/executive economic context. How much annual commission is attached to the accounts the person services? This tells the owner the economic weight of the responsibility. It is not commission personally generated or earned by the account manager, or an account-manager KPI available in that workspace.
How should transfers, acquisitions, and carrier moves be handled?
Separately. If a client moves from one account manager to another, the agency did not grow and the client was not lost. One person's assigned book decreased and another's increased. That transfer has to stay visible or both performance records become misleading.
Acquired books create the same problem at a larger scale. Business that arrived through an agency acquisition increases responsibility, but it is not organic new business for the person who received it. The opening book, acquired arrivals, and internal transfers should be named before anyone interprets growth.
Rewrites and carrier moves stay with the retained policy. Counting by policy number makes the old policy look lost and the replacement look new even though the account manager did the work required to keep the relationship.
Why should owners use both year-over-year and year-to-date views?
Insurance books are seasonal. Renewal concentrations, carrier changes, and a few large accounts can make one month look unusually strong or weak. Comparing adjacent months can turn the calendar into a performance story.
A rolling twelve-month view shows a complete cycle and is usually the steadier reading. A year-to-date view answers what has happened in the current calendar year. Each should be compared with the equivalent prior-year window: twelve months against the prior twelve months, and this year's elapsed months against the same elapsed months last year.
Book-size figures remain a current snapshot. Movement, retention, and new or lost business belong to a stated period. Putting both on one screen is useful only when the distinction stays visible.
What can these numbers not tell you?
They cannot tell you whether an account manager gives sound coverage guidance, communicates well with clients and carriers, keeps records clean, supports colleagues, or handles a difficult book with good judgment. They also cannot reveal every difference in workload. A contractor-heavy commercial book and a straightforward personal-lines book can demand very different amounts of service at the same premium.
The numbers also inherit the agency's operating conditions. Weak producer follow-through, carrier disruption, understaffing, poor source data, or a badly assigned book can all appear in an individual's results.
That is why Book analytics should support a performance conversation rather than complete one. The owner still needs service standards, workload context, client or carrier feedback where appropriate, and the account manager's own explanation of the period.
What should the monthly conversation look like?
Start with the opening responsibility and any book handed in or out. Then read client retention, premium renewed, new and lost business and rounding. Compare the same window with last year and ask where the pattern changed, keeping assignment history, workload and service context visible.
The result should be a short set of questions, not a rank: Which losses were preventable? Did remarketing preserve relationships that the policy counts call churn? Is rounding improving because reviews are happening, or because the book mix changed? Did a transfer create apparent growth? In a separate owner/executive economic view, ask whether the commission attached to the book matches the complexity and workload required to service it.
A useful review ends with one or two agreed actions and a definition of what will be checked next month. If it ends with a composite score nobody can reconstruct, the measurement has replaced the conversation it was supposed to improve.
What a coaching view can show
Each account manager's book, on the same period.
 Department manager viewOpen this page in the live demo →
Fictional Keelridge Demo Agency, twelve months to September 30, 2026. The manager view lists each person's organic and total premium growth, client retention, premium renewed, net cross-sell and new business. No commission. It is a starting point for a coaching conversation, not an employee score.
What to do with this in your own agency
Choose one account manager and reconstruct the last twelve months of their book: opening clients, client retention, premium renewed, new business, lost business, hand-overs and rounding. Keep assignment history, workload and service context beside the figures. Owners and executives can separately review the book's annual commission as economic context. If the numbers cannot explain how the opening responsibility became the closing book, they are not ready to evaluate the person responsible for it.
Sources used for the industry context
- Insurance Journal: Account Manager and CSR Roles and PerformanceAgency-management guidance on defining the role first, comparing like Books, and interpreting productivity alongside workload, line mix, and producer support.
- Indio: Measuring Account Managers' PerformanceIndustry discussion of why Book size and retention percentages alone cannot capture account-manager performance, service quality, or team contribution.